Fixed vs. Variable Annuities 2026: Retirement Security Guide
Understanding the distinctions between fixed and variable annuities in 2026 is essential for securing a stable and growth-oriented retirement income plan.
As we navigate the complexities of financial planning in 2026, a critical decision for many approaching or in retirement involves evaluating fixed vs. variable annuities in 2026. This choice can significantly shape your financial security, offering diverse pathways to income generation and capital preservation. Let’s explore which option might best align with your retirement aspirations.
Understanding Annuities: A 2026 Perspective
Annuities serve as a contractual agreement between you and an insurance company, designed to provide a steady stream of income during retirement. In 2026, the landscape of retirement planning continues to evolve, making a clear understanding of annuity types more crucial than ever. These financial products are often considered for their ability to offer longevity protection, ensuring you don’t outlive your savings.
The primary appeal of annuities lies in their income guarantees, which can be particularly reassuring in an uncertain economic climate. They convert a lump sum or series of payments into regular disbursements, providing a predictable financial foundation for your later years. However, not all annuities are created equal, and their features can vary significantly, impacting your overall retirement strategy.
The Core Purpose of Annuities
At their heart, annuities are about creating a reliable income stream for retirement. They are insurance products first, designed to mitigate the risk of outliving one’s assets. This distinction is important because it frames how annuities operate and the benefits they offer compared to other investment vehicles.
- Longevity Insurance: Annuities can guarantee income for life, offering peace of mind.
- Tax-Deferred Growth: Earnings within an annuity grow tax-deferred until withdrawn.
- Customizable Payouts: Options range from lump sums to regular income streams.
In conclusion, understanding the fundamental role of annuities in 2026 retirement planning is the first step toward making an informed decision. They offer a unique blend of security and income potential, tailored to various financial needs and risk tolerances.
Fixed Annuities in 2026: Stability and Predictability
Fixed annuities, in the context of 2026, remain a cornerstone for retirees prioritizing safety and predictable income. These products offer a guaranteed interest rate for a specified period, or sometimes for the life of the contract, providing a clear picture of your future earnings. This predictability is especially attractive in volatile markets, shielding your principal from market downturns.
The allure of fixed annuities lies in their simplicity and security. You know exactly what your money will earn, and your principal is generally protected. This makes them a suitable option for those with a low-risk tolerance or individuals looking to balance a more aggressive investment portfolio with a stable income source.
Key Features of Fixed Annuities
When considering fixed annuities in 2026, several features stand out. These characteristics define their role in a retirement portfolio and help differentiate them from other financial products.
- Guaranteed Interest Rates: Your money grows at a predetermined rate, regardless of market performance.
- Principal Protection: Your initial investment is safe from market fluctuations.
- Predictable Income: Future income streams are clearly defined, aiding in budgeting.
- Simplicity: They are generally easier to understand compared to variable annuities.
While the returns on fixed annuities might be lower than what could be achieved in a booming stock market, the trade-off is the elimination of market risk. For many retirees in 2026, this certainty is a valuable asset, allowing for more confident financial planning. The stability they offer can be a significant comfort, especially when other income sources might be less secure.
In summary, fixed annuities in 2026 offer a straightforward path to secure, predictable retirement income. They are an excellent choice for those who value peace of mind and protection of their initial investment above potentially higher, but riskier, returns.
Variable Annuities in 2026: Growth Potential and Market Exposure
Variable annuities in 2026 present a different proposition, appealing to individuals seeking growth potential for their retirement savings, even if it comes with market risk. Unlike fixed annuities, the value of a variable annuity, and the income it generates, can fluctuate based on the performance of underlying investment subaccounts, which are similar to mutual funds.
This market exposure means that while you have the potential for greater returns, you also bear the risk of losses. For those with a longer time horizon until retirement or those comfortable with market volatility, variable annuities can offer a way to participate in market gains while still benefiting from the tax-deferred growth and potential income guarantees that annuities provide.
Understanding Subaccounts and Riders
The performance of a variable annuity is directly tied to the subaccounts chosen by the investor. These subaccounts can range from stock funds to bond funds, allowing for diversification based on individual risk tolerance. Additionally, variable annuities often come with optional riders that can enhance their features.
- Investment Subaccounts: Offer diversification and exposure to various market sectors.
- Guaranteed Living Benefit Riders: Can protect against market downturns, ensuring a minimum income stream.
- Guaranteed Death Benefit Riders: Ensure beneficiaries receive at least the initial investment, regardless of market performance.
The flexibility of variable annuities in 2026 allows for a more personalized investment approach within the annuity structure. However, it’s crucial to understand that these benefits often come with higher fees, including investment management fees, administrative fees, and charges for optional riders. These fees can significantly impact overall returns, so a thorough cost-benefit analysis is essential.
In conclusion, variable annuities in 2026 are best suited for those willing to accept market risk for the potential of higher returns. They offer flexibility and growth opportunities, but require careful consideration of fees and investment choices.
Key Differences: Fixed vs. Variable Annuities in 2026
When you’re evaluating fixed vs. variable annuities in 2026, the core distinctions revolve around risk, return, and predictability. These differences are fundamental to deciding which product aligns best with your retirement goals and personal financial philosophy. Understanding these contrasts is paramount for making an informed choice that supports your long-term security.
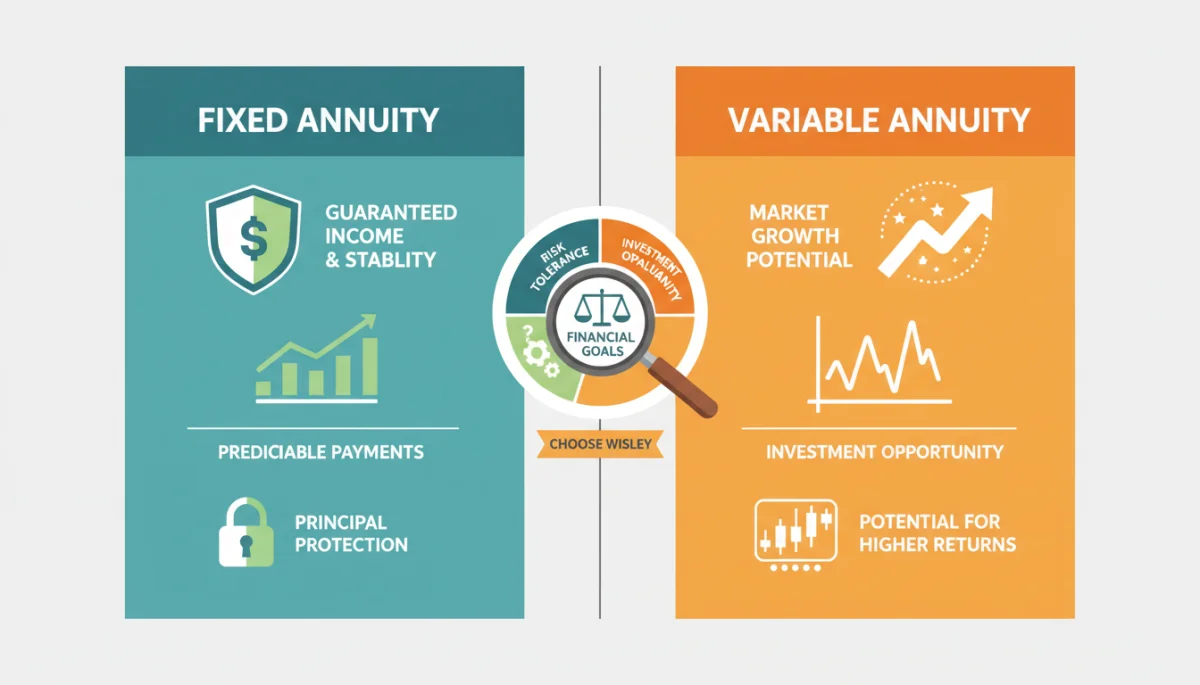
Fixed annuities offer a clear, guaranteed interest rate and principal protection, making them the choice for those who prioritize safety and predictable income. Their value does not fluctuate with market conditions, providing a steady, reliable growth path. This makes them ideal for conservative investors or those seeking to de-risk a portion of their retirement portfolio.
Risk and Return Profiles
The risk and return profiles are perhaps the most significant differentiators between these two annuity types. Your comfort level with market volatility will largely dictate which option is more suitable for your financial plan.
- Fixed Annuities: Low risk, lower but guaranteed returns. Principal protected.
- Variable Annuities: Higher risk, potential for higher returns (or losses). Market-dependent.
Variable annuities, conversely, expose your investment to market fluctuations through subaccounts. This means your returns can be significantly higher during bull markets but can also experience losses during downturns. While they offer growth potential, they also require a higher tolerance for risk and a more active role in monitoring investment performance. The inclusion of riders can mitigate some of this risk, but typically at an additional cost.
Furthermore, fees associated with variable annuities tend to be higher due to the management of subaccounts and the cost of riders. Fixed annuities generally have lower fees, contributing to their appeal for those seeking simplicity and cost-effectiveness. In conclusion, the choice between fixed and variable annuities in 2026 boils down to your personal risk appetite, desired growth potential, and willingness to pay for added features and flexibility.
Factors to Consider When Choosing in 2026
The decision of whether to opt for a fixed or variable annuity in 2026 is highly personal, influenced by a variety of factors unique to your financial situation and retirement aspirations. There’s no one-size-fits-all answer, making a careful evaluation of your circumstances essential. Considering these factors will help you align your choice with your broader financial strategy.
Your current age and time horizon until retirement play a significant role. Younger individuals with more time to recover from market fluctuations might lean towards variable annuities for their growth potential. Those closer to retirement, or already retired, may prioritize the security and predictability offered by fixed annuities to preserve capital and ensure a stable income stream.
Assessing Your Financial Landscape
A comprehensive assessment of your financial health, including existing assets, liabilities, and other income sources, is crucial. This holistic view helps determine how an annuity fits into your overall retirement plan.
- Risk Tolerance: How comfortable are you with market volatility and potential losses?
- Income Needs: Do you need a guaranteed income stream, or are you seeking growth?
- Time Horizon: How many years until you plan to retire or need the income?
- Existing Portfolio: How would an annuity complement or diversify your current investments?
Another critical aspect is understanding the fee structures of each annuity type. Variable annuities often come with a more complex fee schedule, including mortality and expense charges, administrative fees, and fees for investment subaccounts and riders. Fixed annuities typically have lower, more transparent fees. These costs can significantly impact your net returns, so thorough due diligence is imperative.
In conclusion, making an informed decision about fixed vs. variable annuities in 2026 requires a deep dive into your personal financial situation, your comfort with risk, and a clear understanding of your retirement income goals. Consulting with a qualified financial advisor can provide invaluable guidance tailored to your specific needs.
The Role of Annuities in a Diversified Retirement Portfolio for 2026
Integrating annuities into a diversified retirement portfolio in 2026 can offer a strategic advantage, providing balance and mitigating risks that other investments might present. Annuities aren’t meant to be the sole component of a retirement plan but rather a complementary piece that enhances overall financial security. Their unique features can fill gaps left by traditional investment vehicles, creating a more robust and resilient financial future.
For instance, fixed annuities can act as a stabilizing force, providing a guaranteed income floor that can buffer against market downturns affecting equity-heavy portfolios. This allows other parts of your portfolio to take on more risk for higher growth potential, knowing that a portion of your income is secure and predictable. It’s about creating a harmonious blend of growth and protection.
Balancing Risk and Security
A well-diversified portfolio aims to spread risk across different asset classes. Annuities, with their insurance features, introduce a layer of security that traditional stocks and bonds often lack.
- Income Floor: Fixed annuities provide a guaranteed minimum income.
- Growth Potential: Variable annuities offer market participation alongside tax deferral.
- Longevity Protection: Both types can provide income for life, addressing the risk of outliving savings.
Variable annuities, on the other hand, can offer tax-deferred growth potential, which can be particularly attractive for those looking to maximize returns within a protected structure. While they carry market risk, the optional riders can provide downside protection or guaranteed income benefits, blending growth with security. This flexibility allows them to be tailored to specific portfolio needs, whether it’s enhancing growth or providing a safety net.
Ultimately, the inclusion of either fixed or variable annuities in your 2026 retirement portfolio should be part of a broader strategy. It’s about building a comprehensive plan that addresses all aspects of retirement income, risk management, and legacy planning. They can provide a valuable component, ensuring a more predictable and secure financial journey through your golden years.
| Feature | Description |
|---|---|
| Risk Profile | Fixed annuities offer low risk; variable annuities carry market risk. |
| Return Potential | Fixed annuities provide guaranteed, lower returns; variable annuities offer higher, market-dependent returns. |
| Predictability | Fixed annuities offer predictable income; variable annuity income fluctuates. |
| Fees | Fixed annuities generally have lower fees; variable annuities have higher, more complex fees. |
Frequently Asked Questions About Annuities in 2026
The primary advantage of a fixed annuity in 2026 is its predictability and principal protection. It offers a guaranteed interest rate for a specified period, ensuring your investment grows steadily without market risk. This provides a stable income stream, crucial for retirement budgeting and peace of mind.
You should consider a variable annuity if you have a higher risk tolerance and seek greater growth potential for your retirement savings. If you have a longer time horizon and are comfortable with market fluctuations, a variable annuity allows you to participate in market gains, potentially yielding higher returns than a fixed annuity.
Yes, annuity fees remain a significant concern in 2026, especially for variable annuities. These can include mortality and expense charges, administrative fees, subaccount management fees, and rider costs. Fixed annuities generally have lower, more transparent fees. Always understand all associated costs as they impact your net returns.
Yes, one of the core benefits of annuities is their ability to provide income for life, effectively protecting you from outliving your savings. This feature, known as longevity insurance, offers a steady income stream for as long as you live, regardless of market performance or how long you live in retirement.
For some, holding both fixed and variable annuities in 2026 can be a wise strategy. This approach allows you to balance the guaranteed income and stability of a fixed annuity with the growth potential of a variable annuity. It can create a diversified income stream, mitigating risk while still pursuing market upside.
Conclusion
The decision to choose between fixed and variable annuities in 2026 is a pivotal one for securing your retirement. Fixed annuities offer the comfort of guaranteed returns and principal protection, ideal for those prioritizing stability. Variable annuities, conversely, provide the potential for greater growth, albeit with inherent market risks. Your ultimate choice should align with your individual risk tolerance, financial goals, and overall retirement strategy. Consulting with a qualified financial advisor can provide invaluable guidance tailored to your specific needs, ensuring a secure and prosperous retirement.